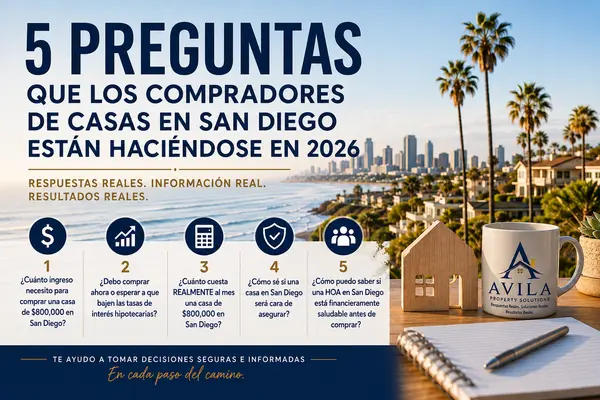
5 Questions San Diego Home Buyers Are Asking in 2026 — Answered
5 Questions San Diego Home Buyers Are Asking in 2026 — Answered
Buying a home in San Diego has always required planning, but in 2026, buyers are navigating a particularly complicated combination of home prices, mortgage rates, insurance costs, property taxes and rising HOA expenses.
As a San Diego real estate professional, these are five of the most important questions I’m hearing from buyers right now — and the answers I think every buyer should understand before starting their home search.
1. How Much Income Do I Need to Buy a Home in San Diego?
There isn't one income number that determines whether you can buy a home. Your purchasing power depends on your down payment, debts, credit, interest rate, taxes, insurance and the specific property you're buying.
But San Diego's affordability numbers put the challenge into perspective.
According to the California Association of REALTORS®' Q2 2026 Housing Affordability Index, affordability remains historically constrained across California as buyers deal with high home prices and borrowing costs. (gov.car.org)
That's why I encourage buyers to start with monthly payment rather than purchase price.
Two buyers earning the same amount can qualify for very different homes because one may have a larger down payment or fewer monthly obligations.
Before deciding that a $700,000, $800,000 or $1 million home is affordable, calculate the complete monthly housing expense:
-
Principal and interest
-
Property taxes
-
Homeowners insurance
-
HOA fees, when applicable
-
Mello-Roos or other special assessments
-
Mortgage insurance, when applicable
-
A reasonable allowance for maintenance
The better question isn't simply, “What price can I qualify for?”
It's:
“What monthly payment am I comfortable living with?”
Those can be two very different numbers.
2. Should I Buy a San Diego Home Now or Wait for Mortgage Rates to Drop?
This may be the question I hear most often.
Unfortunately, nobody can reliably predict exactly where mortgage rates or San Diego home prices will be six or twelve months from now.
What we do know is that financing costs continue to have a major effect on affordability. C.A.R. reported an effective mortgage rate of 6.54% for Q2 2026, compared with 6.24% the previous quarter. (car.org)
So should you wait?
It depends on why you're waiting.
If buying today would stretch your finances beyond what you're comfortable paying, waiting can make sense.
But waiting only because you're expecting a dramatically lower interest rate involves another risk.
If rates fall, you may not be the only buyer who notices.
Lower rates can increase purchasing power and potentially bring more buyers back into the market. Meanwhile, the house you want isn't guaranteed to become less expensive.
I prefer looking at the decision differently:
Can we find a home you like, at a price and monthly payment you can comfortably afford today?
If the answer is yes, buying can make sense regardless of our prediction about next year's interest rates.
And if rates eventually decline enough to make refinancing financially worthwhile, refinancing may become an option.
Buy based on today's numbers. Treat a future refinance as a potential benefit — not something your purchase depends on.
3. What Does a San Diego Home REALLY Cost Per Month?
The mortgage payment is only part of the cost of owning a home.
This is one of the areas where buyers can get surprised.
For example, a buyer searching for an $800,000 home shouldn't simply look at an online mortgage calculator and assume that principal and interest represent the complete monthly expense.
You also need to consider property taxes, homeowners insurance, HOA dues, special assessments, maintenance and potentially mortgage insurance.
There's another California expense first-time buyers sometimes don't anticipate:
The Supplemental Property Tax Bill
When a California property changes ownership, the property is generally reassessed. The resulting difference in assessed value can create a supplemental tax bill in addition to the regular property tax bill. (boe.ca.gov)
San Diego County also explains that some properties have Mello-Roos, a special assessment used to finance public facilities such as schools and roads. (sandiegocounty.gov)
That's why I want my buyers to understand the numbers before writing an offer.
Instead of asking:
“What's my mortgage payment?”
Ask:
“What will this particular property realistically cost me every month?”
That's the number that matters.
4. How Do I Know if a San Diego Home Will Be Expensive to Insure?
Homeowners insurance has become something California buyers need to investigate much earlier in the buying process.
Don't assume that because the current homeowner has insurance, you'll automatically receive the same coverage at a similar price.
A property's location, wildfire exposure, age, roof, construction characteristics and other factors can affect availability and cost.
My recommendation is simple:
Get an insurance quote early.
Ideally, investigate insurance while you still have the appropriate contractual protections rather than discovering late in the transaction that coverage is considerably more expensive than anticipated.
California's Department of Insurance recommends shopping among insurers and brokers when obtaining residential coverage. For homeowners unable to find coverage in the traditional market, the California FAIR Plan is available as a last-resort option, although its basic coverage is more limited and may need to be supplemented. (insurance.ca.gov)
Insurance isn't something I would treat as an afterthought anymore.
The price of the house matters. The cost of protecting it matters too.
5. How Can I Tell if a San Diego HOA Is Financially Healthy Before I Buy?
A condo or townhome can be an excellent way to buy in San Diego — particularly when detached homes are outside a buyer's desired price range.
But when you buy into an HOA, you're evaluating more than the home.
You're also buying into the financial health and obligations of the association.
And that deserves serious attention.
About 57% of San Diego County homes listed for sale in 2025 had HOA dues, according to Realtor.com data reported by Axios, while rising insurance expenses have put additional pressure on association costs. (axios.com)
Before purchasing an HOA property, some of the questions I want answered include:
-
How well funded are the reserves?
-
Are special assessments pending or being discussed?
-
Is major maintenance coming?
-
What does the master insurance policy cover?
-
Has the HOA experienced significant insurance increases?
-
Is there pending litigation?
-
Have HOA dues increased significantly?
-
Are there issues that could affect financing?
This is why the lowest HOA payment isn't necessarily the best HOA.
An association charging very low dues but failing to adequately prepare for future repairs can potentially create a much bigger expense later.
Don't evaluate an HOA based solely on its monthly fee. Evaluate its financial health.
So, Is 2026 a Good Time to Buy a Home in San Diego?
There isn't a universal answer.
For some buyers, absolutely.
For others, waiting and improving their financial position may be the better decision.
My job isn't to convince someone that they need to buy a house.
It's to help them understand the numbers, the property and the potential risks well enough to make an informed decision.
If you're thinking about buying in San Diego County, I can help you determine what homes realistically fit your budget, estimate the true monthly costs and identify issues involving taxes, insurance, HOAs and property condition before they become expensive surprises.
You don't need to be ready to make an offer to start the conversation.
Thinking About Buying a Home in San Diego?
Lawrence Avila
Avila Property Solutions | Coldwell Banker West
DRE #02087637
📞 619-363-4942
✉️ Lawrence@AvilaPropertySolutions.com
🌐 AvilaPropertySolutions.com
Real Estate. Real Solutions. Real Results.
This article is for general informational purposes and is not financial, lending, tax, insurance or legal advice. Buyers should consult the appropriate licensed professionals regarding their individual circumstances.
Categories
- All Blogs (8)
- Buying a Home in San Diego (6)
- California Homeowners Insurance (2)
- First-Time Home Buyer San Diego (4)
- San Diego HOA (1)
- San Diego Home Affordability (6)
- San Diego Home Buyers (6)
- San Diego Home Buying (6)
- San Diego Housing Market, (6)
- San Diego Mortgage Rates (3)
- San Diego Property Taxes (1)
Recent Posts
GET MORE INFORMATION